Yacht Financing: Loan Rates, Down Payment and Monthly Cost (2026)
How much does yacht financing cost? See 2026 marine loan rates, typical down payments, and monthly payment examples for 10, 15 and 20 year terms.
Most buyers do not pay for a yacht in cash. Financing turns a large purchase price into a monthly payment, but it also adds interest, lender conditions and a cash requirement at closing. This guide shows what marine lenders typically ask for in 2026, how the numbers move when you change the rate, term or down payment, and which costs sit outside the loan payment.
Quick answer
Expect to put down roughly 10% to 20% of the purchase price, with larger down payments helping on older or harder-to-value vessels. Published 2026 guides put typical marine loan rates somewhere between about 6.5% and 10% for qualified borrowers, with lender advertising starting near 6.35% APR. On a $400,000 loan at 7.5%, the monthly payment is about $4,748 over 10 years, $3,708 over 15 years and $3,222 over 20 years.
Typical yacht loan rates in 2026
Marine loan rates are not published as consistently as mortgage rates, so quotes vary by lender, credit profile, loan size and vessel age. Sources disagree on the exact range: some lender pages advertise rates starting around 6.35% APR, while consumer finance guides cite typical bands from 6.5% to 10%, and some put the upper end higher for weaker credit. Treat any single number as an indication and get written quotes from several lenders, including credit unions, which are often competitive on marine loans.
Rates generally improve with a higher credit score (guides often cite scores around 720 and above for the best pricing), a larger down payment and a newer vessel.
How much down payment do you need?
Most marine lenders look for 10% to 20% down on a secured loan. Some guides note that custom builds and hard-to-value vessels can require 20% to 30%, and that vessel age tends to shorten the loan term more than it raises the down payment. A bigger down payment can also partly offset a lower credit score.
The down payment goes to the seller, not the lender. If you already own a boat, its appraised value minus its payoff balance can count toward the new down payment.
| Down payment | Cash down | Loan amount | Monthly payment (15 yrs, 7.5%) |
|---|---|---|---|
| 10% | $50,000 | $450,000 | $4,172 |
| 20% | $100,000 | $400,000 | $3,708 |
| 30% | $150,000 | $350,000 | $3,245 |
Example on a $500,000 yacht. Illustrative calculation.
Monthly cost: how loan term changes the payment
Term has a bigger effect on the monthly number than most buyers expect. A longer term lowers the payment but raises total interest sharply. Many lenders offer terms from 10 to 20 years, with the longest terms usually reserved for larger loans and strong borrowers. Older vessels typically face shorter maximum terms.
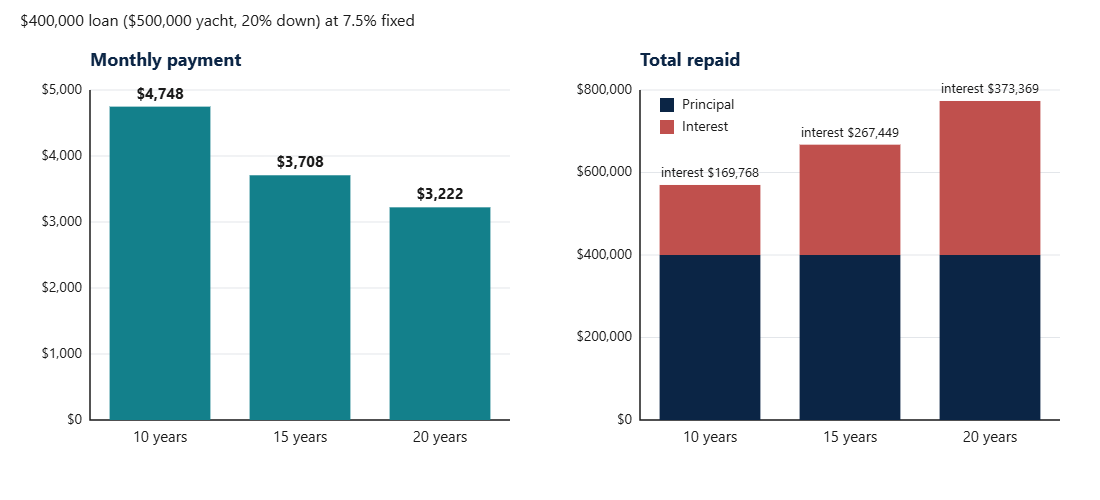
| Term | Monthly payment | Total repaid | Total interest |
|---|---|---|---|
| 10 years | $4,748 | $569,768 | $169,768 |
| 15 years | $3,708 | $667,449 | $267,449 |
| 20 years | $3,222 | $773,369 | $373,369 |
$400,000 loan ($500,000 yacht, 20% down), 7.5% fixed rate, standard amortization. Illustrative calculation, not a lender quote.
Going from 10 to 20 years cuts the payment by about $1,526 a month, but adds roughly $203,601 in interest.
How the interest rate changes the payment
| Rate | Monthly payment ($400,000, 15 years) |
|---|---|
| 6.5% | $3,484 |
| 7.5% | $3,708 |
| 8.5% | $3,939 |
| 9.5% | $4,177 |
Each full percentage point costs roughly $231 more per month on this loan, so shopping several lenders is worth the time.
What the loan payment does not cover
The loan is only one line of the budget. Running a yacht commonly costs around 10% of its value per year, and often more on larger vessels. Plan separately for:
- Marina berth or dockage (marina fees)
- Insurance, which lenders require (yacht insurance cost)
- Maintenance and refit (yacht maintenance cost)
- Fuel (yacht fuel cost) and crew (yacht crew cost) on larger yachts
- Pre-purchase survey (how much a yacht survey costs) and sea trial before closing
Use the annual cost calculator to put the loan payment next to these annual costs, and see how much it costs to own a yacht for the full picture.
Checklist before you apply
- Get a pre-approval or written quotes from at least three lenders, including a credit union.
- Ask for a fixed rate and confirm there is no prepayment penalty.
- Check the lender's minimum loan size and maximum term for the vessel's age.
- Make the purchase agreement subject to survey, sea trial, financing and insurance (see the used yacht survey checklist).
- Keep cash reserves for the first-year costs, not only the down payment.
Frequently asked questions
What credit score do I need for a yacht loan?
Lenders do not publish one fixed minimum. Consumer guides commonly cite scores around 720 or higher for the best rates, while lower scores can still qualify with a larger down payment and a higher rate.
Can I get a 20-year yacht loan?
Often yes, but it is typically a product for larger loans, strong credit and newer vessels. Many lenders set a minimum loan amount (some advertise $50,000), and older vessels usually get shorter terms.
Is a bigger down payment always better?
It lowers the loan, the monthly payment and total interest, and it can improve approval odds. The trade-off is liquidity: keep enough cash for ownership costs after closing.
Are marine loan rates fixed or variable?
Most marine loans use fixed rates, so the payment stays the same for the life of the loan. A few products are adjustable, which means the payment can rise if rates do.